Ever feel like your hard-earned cash vanishes faster than you can track it? 💸 You’re not alone! Many of us struggle to build substantial wealth because our entire income lands in one place, blurring the lines between daily needs and future aspirations. 🤷♂️ But what if achieving significant financial growth wasn’t about drastic austerity or complex financial wizardry? ✨
At SmartSave.top, we believe in smart, sustainable strategies. One of the most powerful, yet remarkably simple, methods for accelerating your savings and investment journey is the Two-Account Strategy. This isn’t about micro-managing every penny; it’s about creating an intelligent system that works for you, automatically separating your spending money from your wealth-building capital. Let’s dive into how this elegant approach can revolutionize your financial future and propel you towards your goals faster than you ever imagined.
🚀Understanding the Core Concept: Separating Your Financial Worlds 🏛️
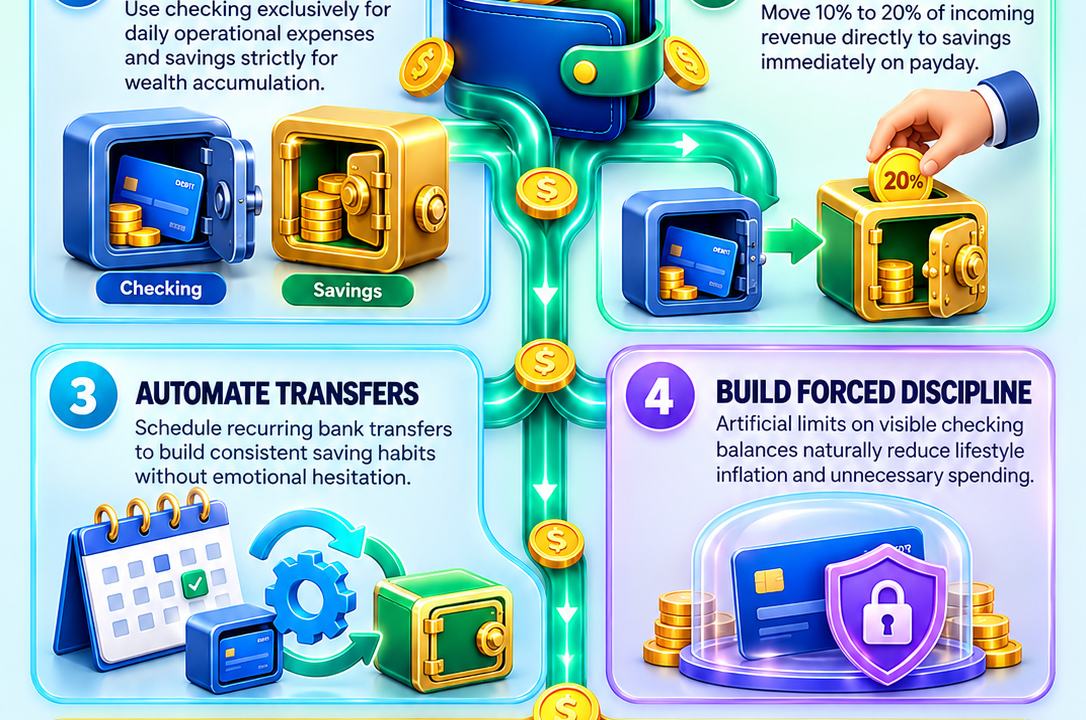
The fundamental principle behind the two-account strategy is elegantly straightforward: create distinct digital “buckets” for different financial purposes. Instead of having one sprawling checking account where everything mixes together, you establish two primary accounts:
1. The Checking Account (Your Operational Hub):This account is where your income directly lands. It’s designated for all your day-to-day expenses: rent or mortgage payments 🏠, utility bills 💡, groceries 🍎, transportation 🚗, entertainment 🎬, and any other costs associated with maintaining your current lifestyle. Think of it as the engine that keeps your present life running smoothly.
2. The Savings/Investment Account (Your Wealth Vault):This is your dedicated sanctuary for long-term financial growth. It’s strictly for accumulating capital, building an emergency fund 🚨, and eventually deploying funds into income-generating assets. This money is consciously set aside, out of sight and out of immediate temptation.
The Power of Psychological Separation 🧠
Why is this simple division so effective? It taps into a fundamental aspect of human psychology – the “balance illusion.” When you see a large sum in a single checking account, your brain subconsciously registers it as available for spending. 🛒 This can lead to impulse purchases and overspending, derailing your savings efforts.
By physically separating your funds, you create a clear mental and practical boundary. Your checking account balance reflects what’s available for this month’s living, while your savings vault represents your future security and growth. This separation significantly reduces the likelihood of accidentally dipping into funds earmarked for your long-term prosperity.
🛡️Key Takeaway: Out of sight, out of mind! By moving your savings to a separate account, you shield them from the immediate allure of everyday purchases.
🛍️The Engine of Growth: Automating Your “Pay Yourself First” Routine ⚙️ The most common saving pitfall is the “leftover” method. Many people try to save whatever money remains after all their bills and spending are accounted for.
📉 The harsh reality? After enjoying life’s pleasures and settling obligations, there’s often precious little, if anything, left to save.
🕳️The two-account strategy flips this paradigm on its head by implementing the powerful principle of “pay yourself first.” This means prioritizing your future financial well-being before allocating funds to discretionary spending. Here’s how the magic happens:
As soon as your paycheck or any income hits your checking account, a pre-determined, fixed percentage (e.g., 10%, 15%, or 20%) is automatically transferred to your dedicated savings or investment account.
This happens before you even look at your balance or consider paying bills. ⚡
..
| Feature | Traditional “Leftover” Method 📉 | Two-Account Automated System 🚀 |
|---|---|---|
| Order of Operations | Income → Spend → Save Leftover | Income → Auto-Save → Spend Remaining |
| Psychological Impact | Feels restrictive, stressful, and guilt-ridden 😬 | Guilt-free lifestyle spending, peace of mind 🧘♂️ |
| Long-Term Wealth | Slow accumulation or stagnation 🕳️ | Consistent compound growth, accelerated wealth building 🌲 |
..
The Power of Automation 🤖 To make this truly effortless, set up recurring automatic transfers. Schedule these transfers to happen on the same day your income typically arrives – payday morning is ideal! ⏰ Automating this process removes the need for manual intervention, willpower, or decision-making. It’s a set-it-and-forget-it system that guarantees your savings grow consistently, month after month, without you even having to think about it. This is where financial discipline becomes less of a struggle and more of an automatic habit.
✅Quick Tip: Integrate your savings transfers with your direct deposit setup if possible! This ensures the money is moved before it even becomes accessible for daily spending.
💯Transforming Savings into Income-Generating Assets
📈Accumulating cash in a high-yield savings account is a fantastic and crucial first step. It builds your emergency fund and provides a buffer. However, letting large sums of money sit idle for extended periods means your purchasing power is gradually eroded by inflation.
🍞 The goal is not just to save, but to make your savings work for you!
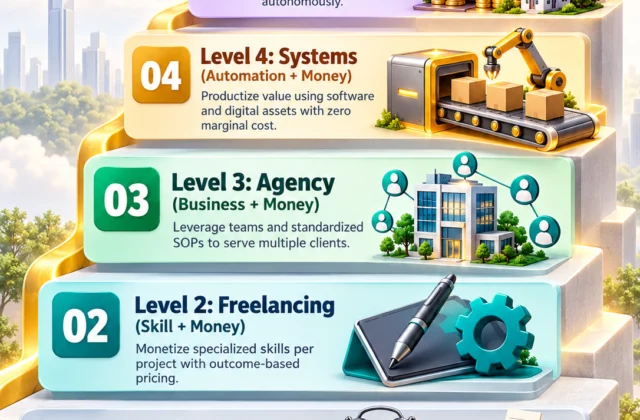
Once your savings account has reached a healthy, comfortable baseline (covering 3-6 months of living expenses), it’s time to deploy that surplus capital into investments that generate returns. At SmartSave.top, we advocate for a diversified approach into several core wealth-building channels:
Real Estate 🏡: Investing in rental properties or Real Estate Investment Trusts (REITs) can provide consistent passive income through rent collection and long-term equity appreciation. It’s a tangible asset that can grow in value over time.
Index Funds 📈: These are incredibly popular for a reason! By investing in index funds, you gain broad exposure to a diverse range of stocks or bonds at a low cost. They offer the power of market compounding over decades with minimal active management, making them ideal for long-term wealth accumulation. Think of it as owning a tiny piece of hundreds or thousands of successful companies. 🌐
Commodities 🪙: Assets like gold, silver, or other raw materials can act as a hedge against economic uncertainty and inflation. They can preserve your purchasing power when traditional markets are volatile. They’re like a financial insurance policy for your portfolio. 🛡️
Side Businesses/Entrepreneurship 🏪: Funding a secondary income stream, an e-commerce venture, or investing in your own skills can dramatically boost your monthly cash flow and accelerate your wealth-building timeline. Turning a passion into a profit center is incredibly rewarding! 💡
By channeling your saved money into these income-producing assets, you transform your capital from a static reserve into a dynamic team of financial workers, consistently generating yield for you. 💎 This is the true essence of building lasting wealth.
Common Pitfall Alert! Never invest money that you will need for essential expenses within the next 1-2 years. Your emergency fund and short-term savings should remain in easily accessible, low-risk accounts. Only deploy genuine surplus capital into investments with a longer time horizon. 🛑
Behavioral Finance: Making Discipline Effortless 🧘♂️
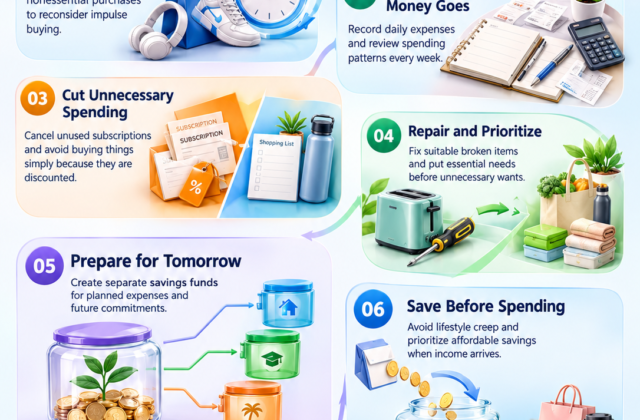
Relying solely on willpower to manage finances is an exhausting battle. 🌊 Behavioral finance teaches us that humans are wired to spend readily available cash. The two-account system elegantly sidesteps this tendency by creating “forced discipline.”
By consistently funneling a portion of your income into your savings vault before you see it, you effectively shrink the amount of readily available cash in your checking account. Your spending habits naturally adjust to fit this new, smaller operating budget. You become accustomed to living within the means of your checking account balance, while your savings vault grows silently and steadily in the background, compounding over time. 🌲
Expert Insight: Once your automated savings transfer has cleared on payday, give yourself full permission to spend the remaining balance in your checking account without guilt or anxiety. 🎉 You’ve already secured your financial future for that period. This psychological shift transforms financial management from a dreaded chore into a seamless, rewarding background habit.
Scaling Your Success: Growing Your Wealth Engine 🌌
The beauty of the two-account strategy is its scalability. As your income increases over time – through raises, bonuses, or successful side hustles – resist the temptation of lifestyle creep. 🐍 Instead of letting that extra money flow into your everyday checking account, continue the practice of directing a significant portion of it directly into your savings and investment accounts. 📈
By consistently increasing the percentage you transfer to your wealth vault as your income rises, you dramatically accelerate your journey towards financial independence. You’re not just earning more; you’re building a more robust and rapidly growing wealth-generating machine. This disciplined approach to income growth is the express lane to achieving your financial dreams. 🏎️
Mini Summary: The two-account strategy is a powerful framework that logically separates your daily spending from your long-term wealth. It automates the critical “pay yourself first” habit, establishes a reliable pipeline for investing in growth assets, and cultivates guilt-free spending, paving a clear path to financial freedom. 🗺️
Key Takeaways for Smart Savers at SmartSave.top 📝
Separate Your Accounts: Designate one account for daily expenses (checking) and another for wealth accumulation and emergencies (savings/investment vault). 💳
Embrace “Pay Yourself First”: Immediately transfer a fixed percentage (e.g., 10-20%) of all incoming revenue to your savings account on payday. ⚙️
Automate Everything Possible: Set up recurring automatic transfers to eliminate human error, procrastination, and emotional decision-making. 🤖
Deploy Surplus Capital Strategically: Once your emergency fund is healthy, invest accumulated savings into income-generating assets like index funds, real estate, commodities, or your own ventures. 🚀
Enjoy Guilt-Free Spending: With your future secured through automated savings, spend the remaining balance in your checking account with complete peace of mind. 🧘♂️
Your Future Starts Now: Take Control of Your Cash Flow Today! 🏁
Achieving robust financial security isn’t solely about how much you earn; it’s fundamentally about how efficiently you manage and grow the money that flows through your hands. 💎 Implementing the two-account strategy is a remarkably simple yet profoundly impactful change. It takes less than twenty minutes to set up, but the dividends it pays throughout your lifetime are immeasurable. 🌲
Don’t delay! Open that second account today, schedule your first automated transfer, and start directing your surplus cash towards income-generating assets. Your future self will be immensely grateful for the proactive steps you take right now. 🚀
Ready to optimize your personal savings roadmap and accelerate your wealth-building journey? Explore the practical budgeting tools, savings calculators, and expert investment guides available here at SmartSave.top. Let’s build your true wealth, together, starting today! 👇