Embarking on the journey to financial well-being doesn’t necessitate a complete overhaul of your lifestyle. 🚀 Often, the most profound transformations stem from a series of small, consistent actions. These manageable steps can powerfully reinforce your budgeting habits, significantly reduce financial stress, safeguard your hard-earned income, and pave the way for substantial long-term wealth accumulation. This comprehensive guide unpacks sixteen accessible strategies, covering everything from the fundamentals of household budgeting and effective saving to assessing your net worth, mastering credit, planning for retirement, leveraging workplace benefits, understanding taxes, fortifying your insurance, organizing crucial financial records, and making mindful lifestyle adjustments. You’ll learn invaluable techniques to accurately track your expenditures, gain a clear overview of your financial standing, implement smarter debt repayment strategies, amplify your retirement contributions, ensure your insurance coverage is adequate, and set meaningful, achievable financial objectives. We’ll also explore simple yet impactful habits, like strategic meal planning and implementing temporary spending pauses to pinpoint areas of potential savings. Whether you’re just beginning your financial expedition or are looking to refine your existing financial blueprint, these steps offer a clear, actionable roadmap to achieve steady progress and cultivate a more organized, resilient financial future, all without resorting to overly complex tactics or drastic sacrifices. Let’s dive in and empower your financial journey! 💪🌟
How Can 16 Small Money Habits Transform Your Financial Health? 🤔
Effective money management is rarely about making dramatic, overnight financial shifts. More often than not, significant financial progress is the result of diligently completing small tasks consistently and making wiser decisions with the resources you already possess. A robust financial plan should extend far beyond simply accumulating savings; it should encompass comprehensive budgeting, astute debt management, maintaining excellent credit health, diligent retirement preparation, adequate insurance coverage, a solid understanding of taxes, meticulous organization of important financial documents, and making realistic, sustainable lifestyle choices. The following sixteen small steps act as a practical financial health checklist, designed to help you construct a more organized, secure, and resilient financial plan. 🗺️
1. Establish a Household Budget: Your Financial Compass 🧭
A household budget is the bedrock of any effective money management system. It provides an indispensable, crystal-clear snapshot of your incoming funds, precisely where your money is being allocated, and how much can realistically be set aside for savings and future goals. 🧾
List Your Income and Expenses: Meticulously record all sources of regular income alongside your essential expenditures. This includes crucial costs like housing (rent or mortgage), utilities, transportation, groceries, minimum debt payments, subscription services, and any other recurring bills. A well-crafted budget effectively categorizes spending into distinct areas: needs (essentials), wants (discretionary items), savings (future security), and debt repayment (reducing financial obligations). Regularly reviewing these categories can illuminate spending patterns that might otherwise go unnoticed, offering valuable insights for optimization. The ultimate aim isn’t just to restrict spending, but to assign a purposeful role to every significant portion of your income. 🎯
2. Set a Defined Monthly Savings Target: Automate Your Success 🏦
Instead of hoping to save whatever might be left at the end of the month, proactively establish a specific, achievable savings amount and treat it as a non-negotiable line item in your regular financial plan. Automating transfers from your checking account to a dedicated savings account can significantly simplify maintaining this habit. Even a seemingly modest amount can grow substantially and become immensely meaningful when contributions are made consistently over time. Think of it as paying your future self! 💰
3. Take a Comprehensive Financial Health Snapshot: Know Where You Stand 📊
Understanding your current financial standing is paramount to effectively measuring and celebrating future progress. This involves taking stock of your overall financial picture.
Calculate Your Net Worth: Determine your net worth by subtracting your total liabilities (debts) from your total assets (what you own). Assets can encompass readily available cash, savings accounts, investments, retirement funds, real estate, vehicles, and any other valuable financial holdings. Liabilities include credit card balances, personal loans, student loans, car financing, and mortgages. The resulting figure offers a concise yet powerful snapshot of your financial position at a given moment. Importantly, a negative net worth doesn’t necessarily signal the impossibility of financial progress; it simply highlights areas where focused improvement is most needed. Periodically tracking this figure can vividly demonstrate whether your assets are growing and your liabilities are diminishing.📈
4. Strengthen Your Credit Management: Your Financial Reputation Matters 💳
Your credit history and score significantly influence your ability to borrow money, the interest rates you’ll be offered, and in some regions, even your insurance premiums and access to various financial products. Therefore, maintaining good credit deserves ongoing attention.
Review Your Credit Reports for Accuracy: Regularly scrutinize your credit reports for any inaccuracies. Look out for unfamiliar accounts, incorrect balances, outdated information, or any other potential errors that could negatively impact your score. If you identify an error, promptly initiate the dispute process outlined by the relevant credit reporting agency or financial institution. Accuracy is key! 🔍
Check Your Credit Score Periodically: Monitor your credit score regularly. While it’s just one component of your overall financial profile, keeping tabs on it helps you understand how lenders are likely to perceive your creditworthiness. Factors such as credit utilization (the amount of credit you use versus your total available credit), payment history, the age of your accounts, recent credit applications, and the mix of credit types you utilize can all influence your score, depending on the specific scoring model used. Knowledge is power when it comes to credit! 💡
Make Minimum Payments on All Debts: To avoid late fees and potential damage to your credit history, ensure you make at least the minimum required payment on every single debt by its due date. After covering these minimums, strategically allocate any additional funds towards high-interest debt or employ another repayment strategy that best suits your financial circumstances. This proactive approach can save you a substantial amount in interest over time. 🛡️
5. Enhance Your Retirement Planning: Secure Your Future 🧑🦳
Effective retirement planning is most successful when initiated early and nurtured gradually. Consistent small steps can make a significant difference in your long-term financial security.
Increase Your Retirement Savings Rate by 1%: Consider a small, manageable increase of just one percent in your retirement contributions. This minor adjustment is often far easier to absorb into your budget than a larger, more drastic cut. As your income evolves over time, you can revisit and adjust your contribution rates accordingly. Don’t forget to maximize employer matching programs where available, as failing to capture this benefit is akin to leaving free money on the table! 💰
Open an IRA: If it aligns with your financial situation, explore opening an Individual Retirement Account (IRA). IRAs offer another powerful avenue for retirement savings, subject to eligibility criteria, contribution limits, specific tax regulations, and account requirements. The most suitable retirement account will depend on various factors, including your income level, available employment benefits, tax bracket, and overarching long-term financial objectives. 📈
Update Retirement Beneficiaries: Regularly review and update the beneficiary designations on all your retirement accounts. Life circumstances change, and it’s crucial that your beneficiary information remains current after significant life events. Keeping these designations accurate ensures your retirement assets will be distributed according to your most current wishes, in compliance with applicable laws and account stipulations. 👨👩👧
6. Review Employment Benefits and Taxes: Maximize Your Compensation 🏢
Employee benefits often represent a substantial component of your overall compensation package, yet they are frequently underestimated or overlooked. Making informed decisions about these benefits can significantly enhance your financial well-being.
Review Available Workplace Benefits: Take the time to thoroughly review the benefits offered by your employer, such as Flexible Spending Accounts (FSAs) or Health Savings Accounts (HSAs). Depending on your eligibility and the specific plan rules, these accounts can be instrumental in managing certain healthcare-related expenses and may offer valuable tax advantages. Beyond health-related accounts, explore other benefits like retirement plans, various insurance options, commuter assistance programs, paid time off, and educational support. Understanding the full spectrum of available options can prevent you from missing out on valuable perks. 💡
Review Your W-4: Periodically review your Form W-4, which informs your employer about the amount of federal income tax to withhold from your paychecks. Significant changes in your income, employment status, number of dependents, or other critical financial circumstances might warrant an update to your withholding information. Tax situations are highly individual, so seeking professional tax advice is advisable when your circumstances become complex. 🧮
7. Strengthen Insurance and Financial Safety Nets: Protect Your Assets ❤️
Sound financial planning extends beyond merely accumulating wealth; it also critically involves protecting your income, assets, and dependents from unforeseen events.
Consider Life Insurance Needs: Evaluate whether life insurance is a necessary component of your personal financial strategy. Your decision should hinge on factors such as having financial dependents, outstanding debts that would need to be covered, your income replacement needs, and any long-term financial obligations you have. Someone who financially supports dependents will likely have different protection requirements than an individual without any financial dependents. The appropriate amount and type of coverage should directly reflect your actual financial responsibilities and peace of mind. 🧘♀️
Check FDIC Insurance Coverage: In the United States, FDIC (Federal Deposit Insurance Corporation) insurance plays a vital role in protecting eligible deposits at FDIC-insured banks. It generally safeguards your funds up to specific limits and under defined ownership categories. Understanding how your various accounts are structured can help ensure that your cash holdings remain within these applicable coverage rules, offering a crucial layer of security for your savings. 🏦
8. Organize Long-Term Financial Records: Accessibility is Key 📋
Having your important financial information readily accessible when needed can save you significant time and stress. A well-organized system ensures you can find critical documents with ease.
Check Your Social Security Statement: For eligible U.S. workers, regularly reviewing your Social Security earnings record and estimated benefits is a prudent step. This allows you to identify any potential discrepancies and gain a clearer understanding of your expected retirement income. Long-term financial planning becomes considerably more robust and reliable when future income streams, like Social Security, are accurately factored into the overall retirement picture. Beyond this statement, ensure all your vital financial records – including tax returns, insurance policies, account statements, property deeds, loan documentation, and estate planning documents – are securely organized and easily retrievable. 📂
9. Set Financial Goals and Adjust Lifestyle Spending: Chart Your Course 🎯
A financial plan truly shines when it effectively links your daily financial decisions to specific, tangible future objectives. This connection provides motivation and direction.
Set One Financial Goal by Year-End: Select a single, measurable, and achievable financial goal to focus on. Instead of creating an overwhelming, vague list of objectives, choose one specific target. This could be building a starter emergency fund, paying down a significant credit card balance, increasing your retirement contributions by a certain percentage, or reaching a defined savings milestone. A truly effective goal should possess a clear monetary target, a defined timeframe for achievement, and a reliable method for tracking your progress along the way. 🗓️
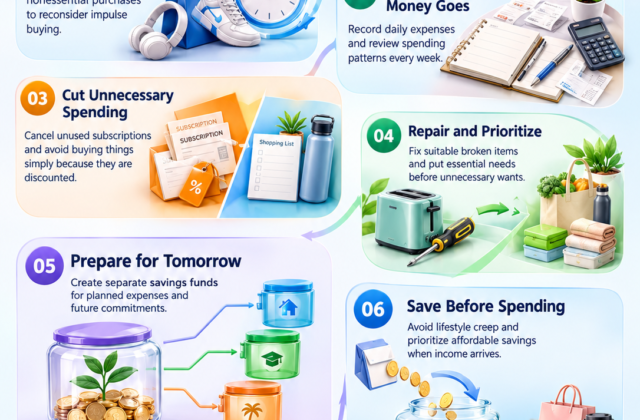
Implement a One-Month Spending Break: Consider undertaking a focused one-month spending review, specifically targeting unnecessary purchases. This doesn’t mean eliminating essential expenses like rent, utilities, or necessary groceries. Instead, critically examine your discretionary spending and identify areas where money might be leaving your budget without providing significant, lasting value. Simple habits like strategic meal planning before grocery shopping can curb impulse buys, while preparing your own lunch can drastically reduce the frequency of buying food during the workday. The objective isn’t long-term restriction, but rather gaining a deeper understanding of your spending behaviors and making informed decisions about which expenditures genuinely support your financial priorities and overall well-being. 🍽️
Why These Small Financial Actions Make a Big Difference 🌟
Financial improvement is often the cumulative effect of combining several modest changes, rather than an elusive search for a single, perfect strategy. A well-managed budget can highlight wasteful spending. Consistent savings build a crucial financial cushion against unexpected events. Smarter debt management drastically reduces the interest costs that can hinder progress. Regular retirement contributions are the engine for long-term wealth creation. Adequate insurance acts as a powerful shield against significant financial disruption. And finally, organized financial records simplify critical decision-making. These areas are intrinsically interconnected. For instance, cutting back on non-essential monthly expenses can free up additional cash flow. This newly available money can then be strategically directed towards building an emergency fund or tackling high-interest debt. Once expensive debt is brought under control, even more resources become available for long-term investing or boosting retirement savings. This creates a virtuous cycle where small, consistent improvements reinforce one another, building momentum towards your financial goals. 🔄
Establishing a Practical Financial Review Routine: Stay on Track 💡
A financial checklist becomes significantly more effective when it’s integrated into a regular review process rather than being a one-time task. Make these reviews a consistent part of your financial life.
Monthly: Review your income, expenditures, savings contributions, debt payments, and any major shifts in your spending patterns. This keeps you agile and responsive. 🗓️
Quarterly: Assess your net worth, review credit information, check progress on financial goals, evaluate insurance needs, and monitor your trajectory towards savings targets. This offers a broader perspective. 📊
Annually: Conduct a deep dive into your retirement contributions, update beneficiary information, re-evaluate workplace benefits, check tax withholding accuracy, confirm insurance coverage details, review your Social Security information, and ensure all important financial records are up-to-date and securely stored. This comprehensive annual review ensures all bases are covered. 🗂️
Not every single task needs to be tackled every month. The core purpose of a regular financial review routine is to bring critical financial decisions into focus before minor issues escalate into larger, more problematic ones. Proactive monitoring is key to sustained success. 🔑
Your Final Takeaway: Small Steps, Big Rewards 🚀
Improving your financial situation doesn’t have to begin with a daunting, complex investment strategy or a radical lifestyle transformation. Start with the fundamental building blocks of financial health: diligently create and stick to a budget, save consistently, accurately calculate your net worth, proactively manage your credit, diligently plan for retirement, fully understand and leverage your workplace benefits, review your insurance coverage, meticulously organize your financial records, and establish clear, measurable financial goals. The most impactful and valuable financial habits are invariably those that can be easily and consistently repeated. By transforming these sixteen small, actionable steps into a regular financial checklist, you empower yourself to gain a clear understanding of where your money is going, fortify your financial stability, and steadily work towards achieving your most ambitious long-term financial aspirations. Your journey to financial freedom starts with these manageable steps! ✨💯