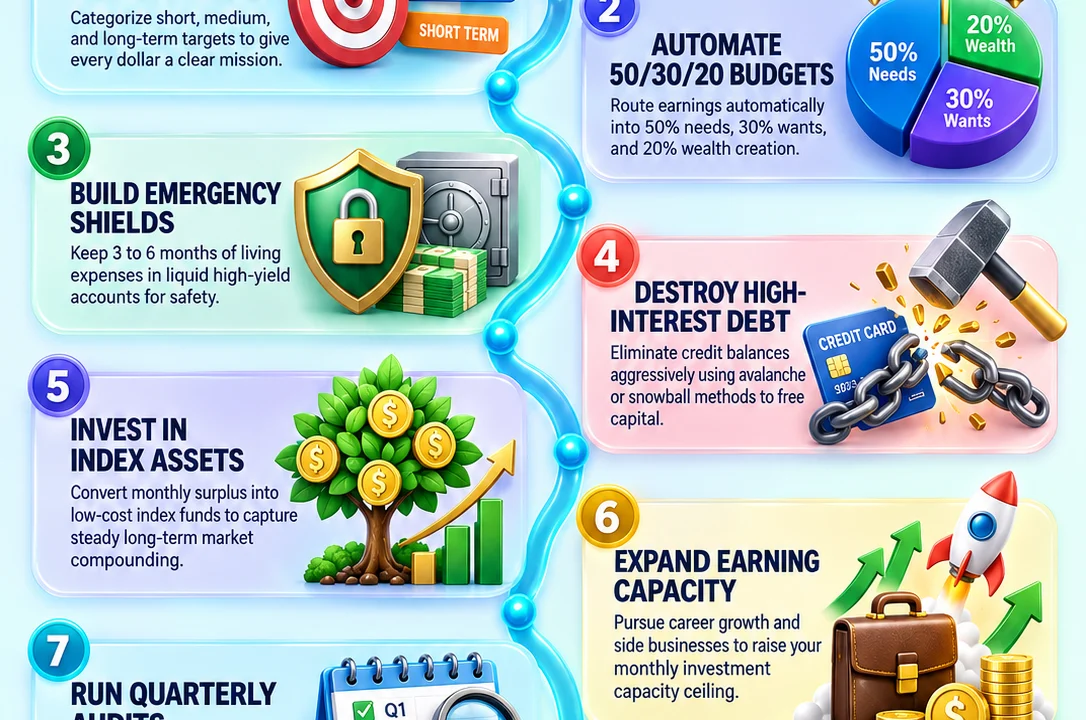
Tired of feeling like your finances are a constant uphill battle? 😩 Wrestling with spreadsheets 📊, agonizing over every purchase 🛍️, and feeling the drain of constant tracking can lead to burnout and decision fatigue. 📉 But what if managing your money didn’t have to be a chore? What if you could build a system that works for you, automating your savings, clearing your debts, and growing your wealth even while you sleep? 😴 This isn’t a pipe dream; it’s the power of a well-designed money management blueprint. 🏛️
True financial health isn’t about drastic sacrifices or tedious manual labor. It’s about creating an autonomous financial engine – a self-running system that directs your money towards your goals without constant intervention. 🧠 We’re going to walk you through the eight core pillars that form the foundation of lasting financial independence. By implementing these steps, you’ll transform your relationship with money from a source of stress to a powerful tool for achieving your dreams. ✨ Let’s dive in and build your path to a secure financial future! 🚀
🎯 1. Define Your Financial North Star: Crystal-Clear Goals with Timelines 🗺️
Imagine setting sail across the ocean without a destination. ⛵ That’s what trying to manage money without clear goals feels like. Vague intentions like “I want to save more” often get lost in the shuffle of daily life and tempting impulse buys. 💸 Setting specific, measurable, achievable, relevant, and time-bound (SMART) financial goals is the first, crucial step to directing your money with purpose. 🎯
Categorizing your aspirations into short, medium, and long-term objectives gives every dollar a mission. This clarity makes it far easier to resist tempting distractions because you know exactly what you’re working towards. It transforms abstract desires into concrete, actionable financial projects. 💎
- 🏖️ Short-Term Goals (0–12 Months): Think about immediate needs and desires like building a starter emergency fund, planning a memorable vacation ✈️, or paying off small, high-interest personal loans.
- 🏡 Medium-Term Goals (1–5 Years): These are the bigger milestones, such as saving for a down payment on your first home 🏠, purchasing a reliable vehicle 🚗, or gathering startup capital for a new business venture.
- 🌲 Long-Term Goals (5+ Years): These are your life-altering ambitions, like accumulating a substantial investment portfolio in index funds for early retirement 🏝️, funding your children’s college education 🎓, or achieving complete financial independence.
Assigning explicit dollar amounts and target dates to these goals creates an emotional connection. When you visualize your future self enjoying the fruits of your current discipline, it becomes much easier to say “no” to unnecessary spending and “yes” to smart financial habits. It’s about making every dollar work harder for your future happiness. 💪
📌 Key Takeaway: Give your money a job! When your funds have a clear assignment and a deadline, they are far less likely to wander off into unnecessary spending. 🕳️
📊 2. Automate Your Income Allocation: The 50/30/20 Rule ⚙️
Traditional budgeting methods, which often involve manual tracking and constant adjustments, can be exhausting. 😩 The key to a sustainable financial system is automation. By setting up automatic transfers on payday, you eliminate the emotional guesswork and enforce healthy financial habits before you even have a chance to spend. 🤖 This proactive approach ensures your priorities are met first.
The 50/30/20 framework provides a balanced, proven baseline for allocating your net take-home pay. This simple rule helps you divide your income into three key areas, ensuring a healthy mix of essential needs, lifestyle wants, and future wealth building. 🧮 By setting up automatic transfers to dedicated sub-accounts as soon as your paycheck arrives, you create a system that consistently prioritizes your financial well-being. 🏦
The Automated 50/30/20 Allocation Model:
| Budget Category 🧮 | Target Percentage 📈 | Included Expenses 🏠 | Automation Strategy ⚙️ |
|---|---|---|---|
| Essential Needs 🏠 | 50% Net Pay | Rent/mortgage, groceries, utilities, insurance, minimum debt payments | Set up auto-bill pay from your primary checking account 💳 for fixed expenses. |
| Lifestyle Wants 🎨 | 30% Net Pay | Dining out, entertainment, hobbies, travel, shopping, subscriptions | Transfer this amount to a separate, dedicated spending account or card for guilt-free enjoyment. 💳 |
| Wealth & Debt 🚀 | 20% Net Pay | Retirement contributions, index fund investments, extra debt payments, high-yield savings | Set up direct deposits to your brokerage account, HYSA, and/or extra debt payment accounts. 🏦 |
💡 Quick Tip: The principle of “paying yourself first” is paramount here. By automating your 20% wealth transfer on payday, you guarantee that your future self is taken care of before discretionary spending even has a chance. This simple act is a powerful habit builder. 🏆
🛡️ 3. Build Your Financial Fortress: A Liquid Emergency Reserve 🏰
Life is unpredictable. 🌩️ Unexpected medical bills, urgent home repairs 🛠️, or sudden job loss are realities that can strike anyone. Without a dedicated financial safety net, these curveballs can quickly derail your progress, forcing you into high-interest debt or compelling you to sell investments at an inopportune time. 📉
A robust emergency fund acts as your personal financial armor, absorbing life’s shocks with minimal disruption. 🛡️ This fund should contain enough liquid cash to cover 3 to 6 months of your essential living expenses. Keeping this money in a high-yield savings account (HYSA) ensures it remains easily accessible while still earning a competitive interest rate. 🧘♂️ This provides immense peace of mind, knowing you’re prepared for the unexpected without jeopardizing your long-term financial goals.
- 🏦 High-Yield Storage: Opt for a separate HYSA. This allows your emergency fund to grow with competitive interest while remaining 100% liquid and readily accessible when truly needed.
- 🛑 Strict Usage Rules: This fund is sacred. It’s strictly for genuine emergencies – unforeseen events that would otherwise cause significant financial hardship. It is not for planned purchases or vacations.
⚠️ Common Mistake: Many people keep their emergency savings in their regular checking accounts. This makes it far too easy for the money to get mixed in with daily spending and accidentally depleted. Always keep it separate! 🕳️
🔥 4. Ignite Your Financial Freedom: Aggressively Tackle High-Interest Debt ⚡
Carrying credit card debt with sky-high Annual Percentage Rates (APRs) – often 20% or more – is like trying to swim upstream against a powerful current. 🌊 The interest charges compound relentlessly, siphoning off precious cash flow that could otherwise be invested in assets that grow your wealth. 💸
Paying off high-interest debt offers a guaranteed, tax-free return equivalent to the interest rate you’re being charged. For instance, paying off debt with a 25% APR is like earning a 25% risk-free return on your money! 📈 Implementing a targeted debt payoff strategy can dramatically speed up your journey to becoming debt-free and permanently free up that cash for wealth-building activities. 🚀
- Debt Avalanche Method: Focus on paying off the debts with the highest interest rates first, while making minimum payments on others. This strategy saves you the most money on interest over time. 💰
- Debt Snowball Method: Prioritize paying off the smallest debts first, regardless of interest rate, while making minimum payments on larger ones. This method provides quick wins and psychological momentum, which can be very motivating. 🏔️
Choosing the right strategy depends on your personality and financial situation. Both are effective, but the avalanche method is mathematically superior for minimizing interest paid. 🧠 Whichever you choose, the key is to be consistent and aggressive. Every dollar freed from interest payments is a dollar you can redirect toward your future. 💪
🌱 5. Cultivate Growth: Systematic Investing for Compounding Wealth 📈
Saving cash is important for liquidity and short-term goals, but simply letting money sit in a traditional savings account means its purchasing power is slowly eroded by inflation over time. 📉 To truly build wealth and secure your financial future, you need to put your money to work. This means converting your cash surplus into productive, yield-generating assets. 💎
Systematic investing, particularly in low-cost, diversified index funds, is one of the most effective ways to harness the power of compounding. 🌳 By investing a fixed amount regularly, such as through dollar-cost averaging, you buy more shares when prices are low and fewer when they are high. This strategy smooths out market volatility, reduces the risk of making large investment decisions at market peaks, and allows your wealth to grow automatically over the long term. 🏛️
Index funds offer instant diversification across hundreds or even thousands of companies, providing broad market exposure with minimal fees. This approach is a powerful, hands-off method for building substantial wealth over decades, aligning perfectly with your long-term financial goals. 💡
📖 Mini Summary: Laying the groundwork for financial health involves setting clear objectives, automating your income distribution, building a robust emergency fund, aggressively eliminating high-interest debt, and consistently investing in growth assets like index funds.
🔍 6. Streamline Your Spending: Smart Audits Without Micromanagement 📱
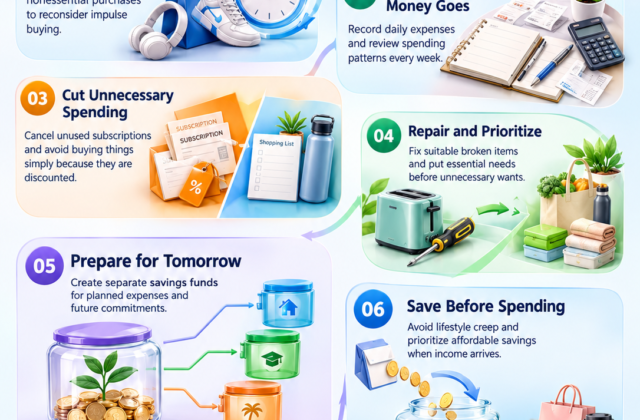
The idea of “budgeting” often conjures images of meticulous tracking of every single penny. 🧾 Thankfully, achieving financial fitness doesn’t require that level of granular detail. Instead of getting bogged down in micro-management, focus on high-level spending audits. A quick 15-minute monthly review is often enough to maintain awareness and prevent costly financial leaks. 🧘♂️
During these brief reviews, look for recurring subscription services you no longer use 🚫, membership fees that have become redundant, or subtle increases in your everyday spending that add up over time (known as lifestyle inflation). 🕳️ The beauty of this approach is that any money reclaimed from these identified leaks can be immediately redirected into your investment account, turning small savings into significant asset growth. 📈 It’s about finding and plugging the holes without overhauling your entire system.
🚀 7. Accelerate Your Wealth Journey: Expand Your Income Streams 💡
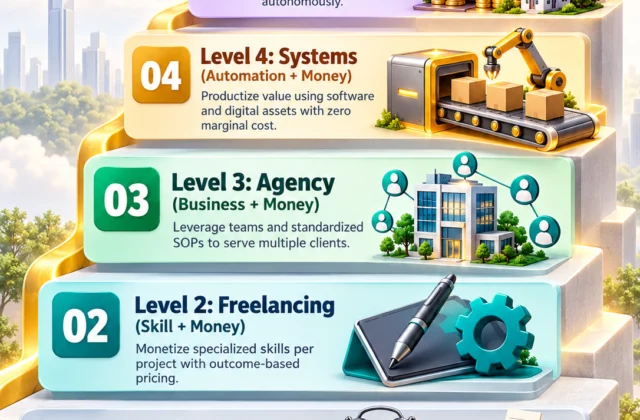
Frugality is a valuable tool in money management, but it has a natural limit – you can only cut expenses down to zero. 🛑 On the other hand, your earning potential has virtually no upper ceiling. 🌌 Actively seeking ways to expand your income streams is one of the most powerful strategies for accelerating your debt payoff, boosting your savings rate, and dramatically increasing your capacity for wealth building. 🏎️
- 💼 Career Advancement: Invest in your professional development. Negotiate merit-based raises ⬆️, acquire in-demand technical skills, pursue strategic certifications, or aim for promotions.
- 🌐 Side Hustles & Freelancing: Monetize your passions and expertise. Offer your services as a freelancer, launch an e-commerce store 🛍️, create digital products, or take on consulting projects that leverage your unique skills.
- 🏛️ Passive Income Assets: Develop streams of income that require minimal ongoing effort. This could include reinvesting dividends from stocks, generating rental income from properties 🏡, or creating intellectual property that earns royalties.
When you combine an increased income with sensible, disciplined lifestyle spending habits, the result is exponential wealth compounding. 🌲 More income means more money available for investing and debt repayment, creating a virtuous cycle of financial growth. 💰
🔄 8. Stay Agile: Quarterly Financial Reviews and Adjustments ⚙️
Life is a dynamic journey, and your financial plan needs to be equally adaptable. 🌊 Major life events like marriage 💍, new job opportunities, career shifts, or significant market fluctuations 📈 necessitate periodic reviews and adjustments to ensure your money remains aligned with your evolving priorities. 🧭
Schedule a dedicated “financial checkup” for yourself every quarter. During these review sessions, take stock of your account balances, rebalance your investment portfolio to maintain your desired asset allocation, and adjust your budget targets as needed. 🗓️ Consistent, periodic reviews are not about drastic overhauls; they are about maintaining long-term momentum, course-correcting when necessary, and ensuring your strategy remains relevant and effective in the face of life’s changes. 🏛️ This proactive approach keeps you on track toward your financial goals.
📝 Key Takeaways for Mastering Your Money 📝
- 🎯 Anchor Your Goals: Clearly define short, medium, and long-term financial milestones with specific, measurable targets.
- ⚙️ Automate Your Splits: Implement the 50/30/20 framework to automatically allocate your income on payday for essential needs, wants, and wealth building.
- 🛡️ Build Cash Buffers: Establish and maintain an emergency fund covering 3 to 6 months of essential living expenses in a liquid, high-yield savings account.
- ⚡ Destroy High APR Debt: Aggressively pay down credit card balances and other high-interest loans using either the debt avalanche or debt snowball method.
- 🚀 Grow Income & Assets: Reinvest any increases in your income directly into diversified investment vehicles like index funds for compounding returns.
- 🔍 Audit Smartly: Conduct brief monthly reviews to identify and eliminate unnecessary expenses and subscription leaks.
- 💡 Expand Earning Power: Focus on increasing your income through career growth and additional revenue streams.
- 🔄 Review & Adjust: Perform quarterly check-ins on your financial plan to make necessary adjustments as your life circumstances change.
🏁 Final Thoughts: Construct Your Autonomous Money Engine Today 🏁
Achieving true financial independence isn’t about luck or extreme deprivation—it’s about thoughtfully designing a reliable financial system that works for you, automatically. 💎 When you minimize friction and automate smart financial habits, consistent progress and long-term wealth accumulation become the natural outcome. 🌲
Take control of your financial destiny starting today. Begin with small, manageable steps: automate just one savings transfer, review your monthly subscriptions, or clearly define your first financial goal. Over time, these consistent, disciplined choices compound powerfully, leading you toward complete financial freedom. 🚀
Ready to optimize your personal financial roadmap? Explore the practical wealth calculators, in-depth investment guides, and robust budgeting frameworks available on SmartSave.top to start building your lasting wealth journey now! 🚀👇