Navigating the world of inherited real estate demands a shift in perspective. It requires looking beyond the sentimental value of a family home and focusing on sound financial decision-making. Let’s delve into the often-overlooked expenses associated with inherited properties and explore how SmartSave.top can guide you in converting these illiquid housing assets into robust, compounding wealth. 🚀
The Unseen Financial Obligations of Inherited Real Estate 🕳️
A house, even one without an outstanding mortgage, is never truly free to own. 🏦 From the moment legal ownership transfers, the new proprietor assumes responsibility for a continuous stream of operational expenses. 📜 Holding onto an old family property without an active income-generating strategy can lead to immediate and significant cash outflows. 📉 These out-of-pocket costs begin accumulating the moment the inheritance is finalized. 🧮
- Property Taxes: Local real estate taxes are an annual obligation that continues to rise, irrespective of whether the house remains occupied or sits vacant.
- Insurance and Utilities: Properties left vacant typically incur much higher insurance premiums compared to standard homeowner policies. Furthermore, essential utilities like electricity, water, and gas often need to be maintained to prevent deterioration, even if no one is living there.
- Deferred Maintenance: Older homes are frequently prone to requiring urgent and expensive repairs. This could range from a complete roof replacement, significant plumbing overhauls, or critical structural upgrades to ensure the property remains sound and safe.
The cumulative effect of paying thousands of dollars annually simply to maintain an unused property can severely deplete personal savings. 🪨
⚠️ Common Pitfall: Delaying decisions about an inherited home for months while deliberating your options is a frequent misstep. Vacant properties deteriorate at an accelerated rate, attract higher insurance costs, and bleed cash daily. 🕳️
Evaluating Your Choices: Retain, Rent, or Relinquish? 📊
Determining the best course of action for an inherited home hinges on a careful evaluation of your current financial objectives and circumstances. 🧭 The three primary pathways – residing in the property, converting it into a rental income source, or selling it outright – each carry distinct advantages and disadvantages. Making an informed decision based on these trade-offs is crucial for safeguarding your long-term financial health. 🧾
| Strategy Option 🛠️ | Primary Advantage 🌟 | Potential Drawback ⚠️ | Best Suited For 🎯 |
|---|---|---|---|
| Sell & Reinvest 📈 | Immediate access to funds and elimination of ongoing property management burdens. | Potential emotional disconnect from cherished family memories tied to the home. | Individuals looking to build diversified portfolios in stocks, bonds, or index funds. |
| Convert to Rental 🏡 | Generates consistent monthly rental income and potential long-term equity growth. | Requires active landlord responsibilities, dealing with tenant issues, and managing maintenance or repair costs. | Savvy investors seeking passive income streams and long-term asset appreciation. |
| Move In Yourself 🔑 | Eliminates current rental expenses or mortgage payments for your primary residence. | Responsibility for all property taxes, upkeep, and potential incompatibility with your current lifestyle or location needs. | Heirs looking to upgrade their personal primary housing situation or relocate to the inherited property’s area. |
💡 Quick Tip: Understand the significance of the ‘stepped-up tax basis’! When you inherit real estate, its tax value is typically adjusted to its fair market worth on the day the original owner passed away. This adjustment can dramatically reduce or even eliminate capital gains taxes if you decide to sell the property. 📜
Strategic Asset Conversion: Liquidating for Growth 📈
A single residential property represents an inherently illiquid asset. 🧱 Concentrating all your inherited wealth within the confines of four walls exposes you to significant risk, especially if local real estate markets experience a downturn. 📉 By selling the property, you gain the ability to convert the equity tied up in the physical structure into liquid capital. This liquidity empowers you to construct a well-balanced and highly diversified investment portfolio. 🧺
- Index Fund Diversification: Reinvesting the proceeds from a home sale across a broad spectrum of global equity markets effectively mitigates the risks associated with a single property’s maintenance issues or market fluctuations.
- High-Interest Debt Elimination: Utilizing the sales proceeds to pay off burdensome personal debts can immediately generate substantial monthly savings, freeing up cash flow and reducing overall financial stress.
Transforming stagnant real estate equity into dynamic, productive market assets is a powerful way to build enduring, multi-generational wealth. 💎
🧠 Expert Insight: Avoid letting emotional attachments cloud your financial judgment! Viewing an inherited house as a strategic capital asset intended for wealth creation will lead to far more beneficial financial decisions than treating it as a sentimental museum piece. 🧘♂️
Navigating Sibling Co-Ownership and Estate Complications 📜
When a property is inherited by multiple individuals, such as siblings or other relatives, it introduces a layer of complexity to co-ownership dynamics. 🧩 When several heirs share equal stakes in a single property, disagreements concerning whether to sell, rent, or occupy the home can frequently arise. 🤷♂️ Establishing clear, objective guidelines from the outset is crucial to prevent family friction and safeguard the underlying value of the inherited asset. 🛡️
- Professional Independent Appraisals: Engaging a licensed, third-party appraiser is essential for establishing an accurate, unbiased baseline market value for the property. This objective valuation serves as a foundation for all subsequent decisions.
- Sibling Buyout Structures: In cases where one heir wishes to retain the property, they can purchase the remaining shares from their siblings. This can be financed through personal funds or a standard mortgage refinance, formalizing the ownership transfer.
Resolving co-ownership issues promptly ensures that the property can be efficiently converted into productive capital before mounting holding costs create undue financial strain on all parties involved. ⚖️
Transforming Inherited Capital into Automated Income Streams 🌲
Once you have successfully liquidated or optimized the value of your inherited property, the ultimate objective is to deploy those funds into assets that generate consistent cash flow. ⚙️ Channeling capital into broadly diversified stock index funds, dividend-paying portfolios, or high-yield savings vehicles creates an automated, hands-off monthly income stream, eliminating the need for landlord responsibilities or responding to maintenance emergencies. 🚀
📖 Mini Summary: Inheriting a home often comes with ongoing tax obligations and maintenance demands. Strategically liquidating or renting out the property allows you to convert illiquid real estate equity into compounding long-term wealth.
Key Takeaways for Property Heirs 📝
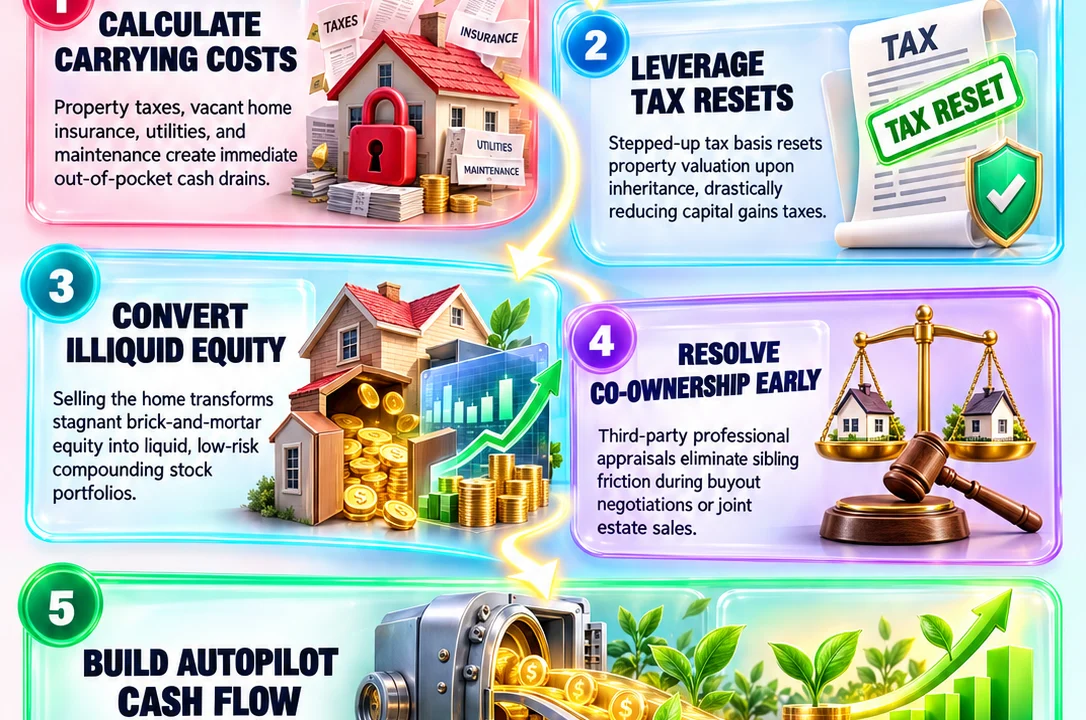
- Calculate Carrying Costs Immediately: Factor in property taxes, vacant property insurance premiums, utility expenses, and potential repair costs from day one.
- Leverage the Stepped-Up Basis: Take full advantage of the tax reset benefit on inherited property to significantly minimize or eliminate capital gains tax upon sale.
- Convert Illiquid Equity: Strategically reinvest the proceeds from a property sale into low-maintenance, diversified index funds for sustainable growth.
- Resolve Co-Ownership Disputes Early: Utilize professional appraisals to facilitate sibling buyouts or to ensure a fair and equitable joint sale.
- Prioritize Hands-Off Cash Flow: Opt for investment strategies that reliably generate predictable, passive income rather than holding onto idle, depreciating real estate.
Final Thoughts: Seize Control of Your Financial Trajectory 🏁
An inherited house possesses the potential to be a powerful financial asset, but only when it is managed with clarity, discipline, and a strategic vision. 💎 By diligently assessing carrying costs, understanding the nuances of tax benefits, and proactively converting equity into productive, income-generating assets, you can transform what might otherwise be a significant financial burden into a sustainable engine for wealth creation. 🌲
Make your property inheritance work for you, starting today. Analyze your ongoing expenses, explore diverse asset conversion strategies, and set your capital on a trajectory of compounding growth. 🚀
Ready to build your personalized wealth conversion roadmap? Explore our practical asset calculators, comprehensive estate strategy guides, and advanced portfolio tools at SmartSave.top to begin compounding your cash flow effectively right now! 🚀👇